Most kids don’t learn about money by accident — they learn it by watching how the adults around them handle it. If you want your child to grow up comfortable with budgeting, saving, and making smart financial decisions, the habits have to start small and start early. This guide walks through why saving matters, when to start, and ten practical tips you can use starting this week, no matter your child’s age or how much allowance you give.
Whether you’re just handing over your first few dollars of pocket money or trying to fix habits that already feel a little off track, this article covers the full picture: age-appropriate strategies, the save-spend-share method, common parenting mistakes, and answers to the questions parents ask most often about teaching kids about money.
Why Teaching Kids to Save Money Matters
Teaching kids to save money gives them practical skills they’ll use for the rest of their lives — financial responsibility, independence, an understanding of effort and value, and better decision-making as adults. These aren’t abstract lessons. They show up in how a teenager handles their first paycheck or how an adult handles an unexpected bill.
Builds Financial Responsibility From an Early Age
A child who saves a portion of their allowance every week is practicing financial responsibility long before they ever pay a bill. They’re learning that money isn’t unlimited, that choices have consequences, and that planning ahead pays off. This kind of early repetition builds habits that are far harder to teach later, once spending patterns are already set.
Encourages Independence and Confidence With Money
When kids manage their own small amount of money — deciding what to buy, what to skip, and what to save — they build confidence in their own judgment. That confidence carries into bigger financial decisions later, from choosing a bank account to managing a first paycheck.
Teaches the Value of Money and Effort
Kids who earn or manage money directly start to connect effort with reward. Saving up for something they actually want teaches them that money represents work, time, or trade-offs — not something that simply appears when needed.
Helps Children Make Better Financial Decisions in the Future
Good money habits formed in childhood tend to carry forward. A child who understands needs vs wants and practices delayed gratification is more likely to become an adult who budgets, avoids unnecessary debt, and thinks before making big purchases.
What is the Right Age to Start Teaching Saving Habits?
There’s no single “correct” age to start — most financial educators agree you can begin as early as age 2 or 3 with very simple concepts, and build in complexity as your child grows. What changes with age isn’t whether to teach saving, but how.
Toddlers and Preschoolers (Ages 2–5)
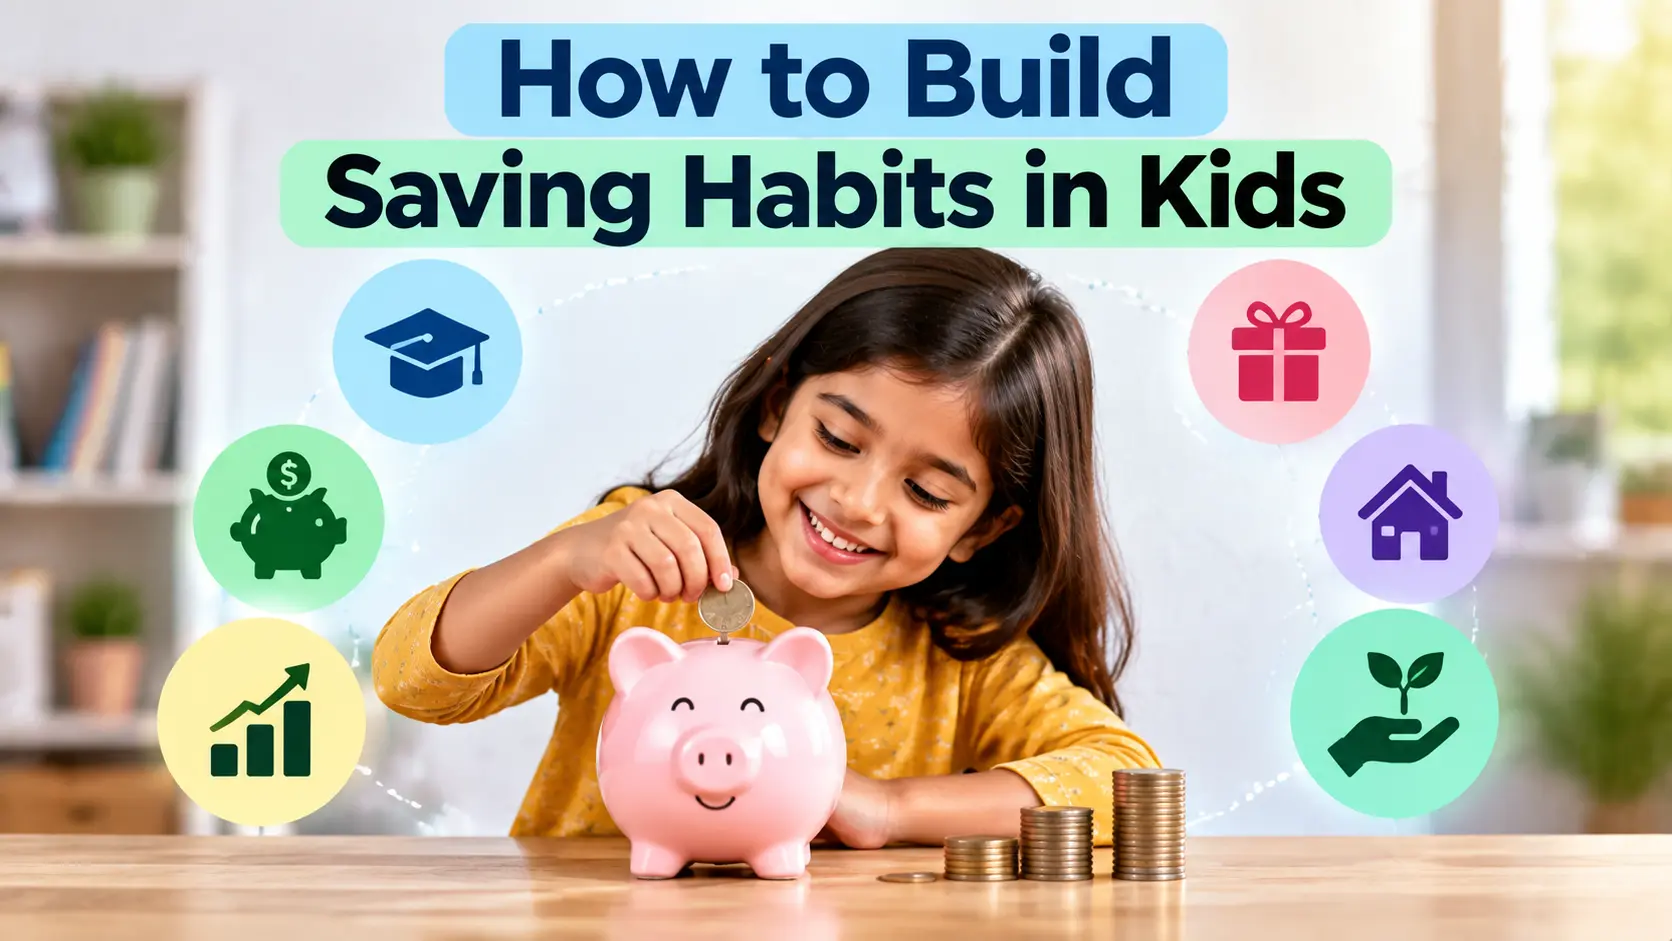
At this age, keep it visual and simple. A clear piggy bank where they can see coins add up, paired with basic language like “save” and “spend,” is enough. Toddlers won’t understand interest rates or budgets, but they can grasp that putting coins in a jar makes the pile grow.
Elementary School Kids (Ages 6–10)
This is typically when allowance, a first savings jar system, and simple saving goals become realistic. Kids at this age can count money, understand short-term goals (“save $10 for a toy”), and start distinguishing needs vs. wants with guidance.
Preteens and Teenagers (Ages 11+)
Preteens and teens are ready for real accounts, actual budgeting, and more responsibility — including a kids’ bank account, tracking their own spending, and setting longer-term saving goals like a phone, a trip, or early planning toward financial independence.
10 Simple and Effective Tips to Build Saving Habits in Kids
Below are 10 effective tips to build saving habits in kids. Let’s explore each tip in detail and understand how they can help children develop better money management skills.
Tip 1: Teach Kids the Difference Between Needs and Wants
The clearest starting point for financial literacy is helping kids sort spending into needs and wants — necessities versus things that are simply nice to have. Once a child can make that distinction on their own, every other money lesson becomes easier to teach.
A simple way to practice this: during a grocery trip or before a purchase, ask your child to sort items into two columns — “need” and “want.” Over time, this becomes second nature. For a deeper breakdown of this concept as it applies beyond childhood, this guide on needs vs. wants is a useful reference for parents who want to explain it more thoroughly.
Tip 2: Introduce Saving Through a Piggy Bank or Savings Jar
For younger kids especially, a physical piggy bank or a set of labeled jars (save, spend, share) makes saving tangible. Seeing coins accumulate is far more motivating for a five- or six-year-old than any explanation of a bank statement would be.
Look for a piggy bank or jar system that’s clear or transparent, so kids can visually track progress. Some parents use three separate jars instead of one piggy bank, which naturally sets up the save-spend-share habit covered in Tip 6.
Tip 3: Open a Kids’ Savings Account and Teach Banking Basics
Once a child is old enough to understand basic math — usually around age 7 or 8 — opening a kids’ savings account turns saving into something real. It shows them how banks work and introduces the idea that saved money can actually grow over time.
Choosing the Right Kids’ Savings Account
Look for a savings account for children with no monthly fees, a low or no minimum balance requirement, and some form of parental oversight or joint access. Many banks and credit unions offer youth-specific accounts with these features, and some also include educational tools or apps built for kids. Comparing a few local banks and credit unions before choosing is worth the extra half hour — fee structures and youth account perks vary widely.
Teaching Basic Banking Concepts (Deposits, Interest, Withdrawals)
Once the account is open, walk your child through the basics in plain language:
- Deposits — putting money into the account
- Withdrawals — taking money out
- Interest — the small amount extra a bank pays for keeping money saved with them
You don’t need to explain interest rates in detail. Showing them their balance grow slightly over a few months, even by a small amount, is often enough to make the concept click.
Tip 4: Give an Allowance and Encourage Smart Money Decisions
An allowance gives kids the chance to practice real decision-making with real (if small) stakes. Whether it’s tied to chores or given unconditionally is a personal choice, but consistency matters more than the amount.
A few allowance approaches that tend to work well:
- A fixed weekly amount, regardless of chores, to build routine
- A chore-based system where specific tasks earn specific amounts
- A hybrid — a small base allowance plus extra for additional chores
Whichever method you choose, resist the urge to top it back up if your child spends it all quickly. Letting them feel the effects of a spending decision is part of the lesson.
Tip 5: Set Savings Goals Together
Kids save far more consistently when they’re working toward something specific rather than saving in the abstract. Sit down with your child and pick a concrete goal — a toy, a game, a bike — and figure out together how much needs to be saved each week to get there.
A simple goal-tracking chart, even a hand-drawn thermometer taped to the fridge, gives kids a visual sense of progress and keeps motivation up between paydays.
Tip 6: Teach the Save, Spend, Share Method
The save, spend, share method divides money into three simple categories the moment it’s received, so kids build the habit of saving before they ever get the chance to spend everything.
Save: Building a Habit of Setting Money Aside
Have your child set aside a fixed percentage — commonly around 30-50% for younger kids — into a “save” jar or account before anything else happens with the money. Doing this first, rather than saving whatever’s left over, is the habit that matters most.
Spend: Learning Smart and Responsible Spending
The “spend” portion is theirs to use on things they want, within reason. This is where smart spending habits get practiced — comparing prices, waiting for sales, or deciding something isn’t worth the money after all.
Share: Developing Generosity and Social Responsibility
A smaller portion set aside for giving — to a charity, a family member, or a cause they care about — helps kids connect money to generosity and social responsibility, not just personal wants.
Tip 7: Teach Kids to Track Their Savings and Spending
Tracking spending, even in a simple notebook or basic app, helps kids see exactly where their money goes and builds awareness they’ll carry into adulthood. Without tracking, saving goals are easy to lose sight of.
For younger kids, a paper chart works fine. For preteens and teens, a basic budgeting or financial literacy app designed for children can make tracking more engaging, often with visual goal trackers or simple charts.
Tip 8: Use Everyday Activities to Build Financial Responsibility
Everyday moments are often better teaching tools than formal lessons. Grocery shopping, paying bills, or comparing prices at the store are all natural opportunities to bring your child into real financial decisions.
A few examples:
- Let them compare prices per unit at the grocery store
- Involve them in planning a family outing on a set budget
- Have them help calculate a tip at a restaurant
Tip 9: Make Saving Fun Through Rewards and Challenges
Saving sticks better when it feels like a game rather than a chore. Simple money games and small challenges — a savings streak, a matching contribution when they hit a goal, or a friendly competition with a sibling — keep kids engaged with saving instead of dreading it.
A popular option is a “savings match,” where a parent adds a small percentage on top of whatever the child saves toward their goal, similar to how employer retirement matches work for adults.
Tip 10: Teach Delayed Gratification and Smart Spending Choices
Delayed gratification — the ability to wait for a bigger reward instead of taking a smaller one immediately — is one of the strongest predictors of long-term financial discipline. Practicing it early, even with small purchases, builds a mental habit that pays off for life.
A simple way to build this skill: when your child wants to buy something impulsively, introduce a short waiting period — 24 hours for smaller items, a week for bigger ones. Often, the desire fades, and the money stays saved.
How Parents Can Lead by Example With Good Money Habits
Kids absorb financial habits from watching parents far more than from any lesson or conversation. If saving, budgeting, and thoughtful spending are visible at home, kids pick up on that pattern naturally — often more effectively than through direct instruction.
Talk Openly About Money at Home
Money doesn’t need to be a secret or a source of tension in front of kids. Age-appropriate conversations about budgeting, saving for a goal, or why a purchase was postponed help normalize money as something to plan for, not something stressful to avoid discussing.
Practice Budgeting and Planning in Front of Your Kids
Letting kids see a family budget being built — even a simple one for groceries or a vacation — shows them what planning actually looks like in practice. For parents who want a refresher on the basics before walking kids through it, these budgeting tips offer a solid starting framework.
Show How You Save Toward Personal Goals
If you’re saving for something — a vacation, a new car, an emergency fund — mention it to your kids and let them see the process. Watching a parent set a goal and stick with it is one of the most effective teaching tools available.
Demonstrate Smart Spending and Avoid Impulse Purchases
Narrating your own decision-making out loud (“I really want this, but I’m going to wait and see if I still want it next week”) shows kids that even adults practice restraint and comparison before spending.
Common Mistakes Parents Make When Teaching Kids About Money
Even well-intentioned parents can unintentionally slow down their child’s financial learning. Recognizing these common mistakes early makes it easier to correct course.
Starting Money Lessons Too Late
Waiting until the teenage years to introduce money concepts means missing years of natural habit-building. Starting simple lessons as early as preschool age gives kids more time to internalize good habits before spending patterns set in.
Giving Money Without Teaching Its Value
Handing over money without any connection to effort, chores, or decision-making can leave kids feeling entitled to money rather than responsible for it. Pairing money with some form of earning or decision-making builds a stronger association.
Avoiding Real-Life Money Conversations
Treating money as a taboo topic at home leaves kids to piece together financial understanding from friends, social media, or guesswork — none of which are reliable sources.
Excluding Kids From Financial Decisions
Kids who are never included in small financial decisions — like choosing between two options within a set budget — miss out on practicing the decision-making skills that come with managing money.
Protecting Kids From Every Financial Mistake
Stepping in every time a child is about to make a small financial misstep removes the natural consequence that teaches the lesson. A small loss, like spending all their allowance on something they later regret, often teaches more than any conversation could.
Being Inconsistent With Allowance and Money Rules
Changing allowance amounts, rules, or expectations frequently makes it hard for kids to plan or trust the system. Consistency is what allows saving habits to actually form.
Focusing Only on Saving and Ignoring Spending Skills
Saving is only half of financial literacy. Kids also need practice with smart spending — comparing options, avoiding impulse buys, and understanding value for money — or they may struggle with spending decisions once they have more financial independence.
Final Thoughts
Building saving habits in kids isn’t about a single lesson or one perfect system — it’s about small, consistent practices repeated over years: a piggy bank at five, a savings account at eight, a real budget by the teenage years. Start with whatever fits your child’s age right now, stay consistent, and let them make some of their own decisions — including a few small mistakes along the way. Those early habits tend to shape how confidently they’ll handle money as adults.
FAQs
What Is the Best Age to Start Teaching Kids About Saving Money?
Most financial educators suggest starting as early as age 2 or 3 with simple, visual concepts like a piggy bank, and building in complexity — allowance, savings accounts, budgeting — as your child grows through elementary and teenage years.
How Can I Teach My Child the Importance of Saving Money?
Connect saving to a goal they care about, let them see money grow toward that goal, and involve them in small financial decisions regularly. Real, hands-on practice teaches the value of saving far more effectively than explanation alone.
What Are the Easiest Ways to Develop Saving Habits in Kids?
The easiest starting points are a visible piggy bank or jar system, a consistent allowance, and one clear savings goal to work toward. These three combined give kids a simple, repeatable structure.
How Much Allowance or Pocket Money Should I Give to Encourage Saving?
There’s no fixed universal amount — many families use a rough guideline of matching the allowance to the child’s age (for example, a small weekly amount per year of age), adjusted for what fits your household budget. Consistency matters more than the specific figure.
How Can Kids Learn the Difference Between Needs and Wants?
Practice sorting exercises during everyday shopping — having kids label items as “need” or “want” before a purchase — builds this skill naturally over time and with repetition.
How Can Parents Help Children Set Savings Goals?
Choose a specific, achievable item or experience together, calculate how much needs to be saved weekly to reach it, and track progress visually with a chart, jar, or simple app.
What Is the Save, Spend, Share Method for Kids?
It’s a system where money is divided into three categories as soon as it’s received: a portion saved, a portion spent freely, and a smaller portion set aside to give or donate. It builds saving and generosity habits simultaneously.
Is a Kids’ Savings Account a Good Way to Teach Money Management?
Yes — a kids’ savings account introduces real banking concepts like deposits, withdrawals, and interest in a low-risk way, and works especially well once a child is old enough (typically around 7-8) to understand basic account balances.
Piggy Bank vs. Bank Account — Which Is Better for Kids?
A piggy bank works best for younger children who need a visual, tangible way to see savings grow. A bank account is better suited for older kids ready to understand real banking concepts. Many families use both — a piggy bank first, then transitioning to an account.
How Can I Make Saving Money Fun for Children?
Turn saving into a game with visual trackers, small savings challenges, or a “match” system where you add a bonus percentage when your child hits a savings goal — similar in spirit to how employer matching works for adult retirement accounts.
How Can I Teach My Child Budgeting and Spending Control?
Start with a simple, small-scale budget — like planning a $20 outing — and let your child make the spending decisions within that limit. Real practice with real limits teaches budgeting far faster than abstract explanation.
What Chores Can Kids Do to Earn Money and Learn Saving Habits?
Age-appropriate options include tidying their room, helping with dishes, yard work, or pet care. Tying specific chores to specific earnings gives kids a direct, tangible connection between effort and money.
What Should I Do If My Child Refuses to Save Money?
Start smaller — a very small savings goal with a fast payoff can rebuild motivation. Involving them in choosing the goal themselves, rather than assigning one, also tends to improve buy-in.
What Are Common Mistakes Parents Make When Teaching Kids About Money?
The most common mistakes include starting too late, giving money without connecting it to effort, avoiding money conversations at home, and focusing only on saving while ignoring spending and budgeting skills.
Disclaimer –
This article is for general informational and educational purposes only and does not constitute financial or professional advice. Savings account features, interest rates, and banking products mentioned may vary by provider and are subject to change. Please research current offers and consult a financial advisor for decisions specific to your family’s situation.